The Global Payment Ecosystem Is Changing: What Regulators, Networks, and Fintechs Are Building Next
12 min read
The global payments industry is entering a new phase.
For years, innovation in payments was largely measured by how quickly a transaction could move from one account to another. Today, the conversation is becoming much broader. Regulators, central banks, payment networks, banks, and fintechs are increasingly focused on interoperability, cross-border connectivity, real-time payments, intelligent fraud prevention, open finance, and programmable financial infrastructure.
The objective is no longer simply to make payments digital. It is to make them faster, more connected, transparent, secure, and accessible across markets.
This shift is creating a new foundation for everything from embedded banking solutions to international commerce.
Instant Payments Are Becoming the New Baseline
Instant payment systems have moved from being a market differentiator to becoming core payment infrastructure.
More than 70 countries now operate instant payment systems capable of moving money within seconds domestically. The next challenge is connecting these systems across borders.
This is where initiatives such as Project Nexus, developed by the BIS Innovation Hub, become significant. Rather than requiring every national payment system to build individual connections with every other country, Nexus proposes a standardised approach for connecting domestic instant payment systems. Its goal is to enable cross-border payments to reach recipients in potentially less than 60 seconds.
The implication for the industry is significant: the future of instant payments may depend less on creating more domestic payment rails and more on making existing rails interoperable.
Cross-Border Payments Are the Next Frontier
Domestic payments have evolved rapidly, but cross-border payments continue to face challenges around cost, speed, transparency, compliance, and interoperability.
The G20 has made improving cross-border payments a major priority, with targets focused on making international payments faster, cheaper, more transparent, and more inclusive.
The current roadmap places particular emphasis on payment-system interoperability, regulatory frameworks, cross-border data exchange, APIs, and common messaging standards.
This is an important shift in thinking.
Instead of treating cross-border payments as a completely separate infrastructure problem, the industry is increasingly exploring how existing domestic systems can communicate with one another.
For global businesses, this could eventually mean fewer intermediaries, improved transaction visibility, faster settlement, and a more consistent payment experience across markets.
India Is Testing What the Next Generation of Payments Could Look Like
India offers an interesting example of how payment infrastructure can evolve beyond traditional card-led models.
Through UPI, the country has developed an account-to-account payment infrastructure supporting real-time person-to-person and merchant payments. NPCI's ongoing initiatives are now extending the ecosystem toward international users, stronger security, AI applications, and broader global acceptance.
One recent example is UPI One World, which was extended in 2026 to international visitors from more than 40 countries, allowing them to make UPI merchant payments without an Indian mobile number or bank account.
NPCI has also announced work around AI for the payments ecosystem, including a domain-specific AI language model and sovereign AI infrastructure initiatives.
These developments are relevant beyond India. They demonstrate a broader industry direction: payment infrastructure is increasingly being designed around interoperability, intelligence, international accessibility, and real-time experiences.
Open Finance Is Moving Beyond National Borders
Another important development is the evolution of open banking and open finance.
Open finance has expanded across numerous jurisdictions, but different technical standards, data formats, authentication mechanisms, and regulatory frameworks have made cross-border data exchange difficult.
BIS Project Aperta is exploring a potential solution through a "network of networks" approach. Its prototype connected open finance networks across the UK, UAE, Brazil, HongKong SAR, and India through an interoperability layer designed to translate between different domestic frameworks while preserving local regulatory and trust requirements.
This approach could have implications well beyond payments.
Cross-border business account opening, trade finance, financial data portability, and international financial services could all benefit from infrastructure that allows systems to communicate without requiring every country to replace its existing architecture.
For businesses operating across multiple markets, this could make embedded banking solutions increasingly dependent on interoperability rather than isolated integrations.
ISO 20022 Is Making Payment Data More Valuable
Payments are not only about moving money. They also generate enormous amounts of financial data.
The adoption of ISO 20022 is helping create more structured and consistent payment information across financial systems. In February 2026, the BIS Committee on Payments and Market Infrastructures published updated harmonisation requirements for ISO 20022 to support greater consistency in cross-border payment messaging.
Better-structured data can support more than messaging efficiency.
It can improve transaction visibility, reconciliation, compliance processes, fraud monitoring, and analytics. As payment ecosystems become increasingly data-driven, the quality and portability of payment information will become just as important as transaction speed.
Tokenisation Could Change How Settlement Works
Another emerging area is tokenisation.
BIS Project Agorá recently demonstrated how tokenised commercial bank deposits and tokenised central bank reserves could operate together on a shared programmable platform for wholesale cross-border payments. The prototype demonstrated the possibility of atomic, multi-currency settlement and programmable transaction logic.
The significance is not simply the use of blockchain or tokenisation.
The larger idea is programmability.
Future payment infrastructure could potentially embed conditions, compliance requirements, settlement rules, and business workflows directly into transactions. That could reduce manual intervention and reconciliation while creating new possibilities for conditional and always-on payments.
What This Means for the Future of Payments
Taken together, these developments point toward a fundamental change in how payment infrastructure is designed.
The next generation of payment systems will likely be:
- Instant, with real-time movement of funds becoming increasingly standard.
- Interoperable, connecting domestic payment systems across jurisdictions.
- Data-rich, using structured payment information to improve visibility and decision-making.
- Intelligent, with AI increasingly supporting fraud detection, operations, and payment infrastructure.
- Programmable, allowing transaction logic and business rules to become part of the payment process.
- Globally connected, reducing the distinction between domestic and international payment experiences.
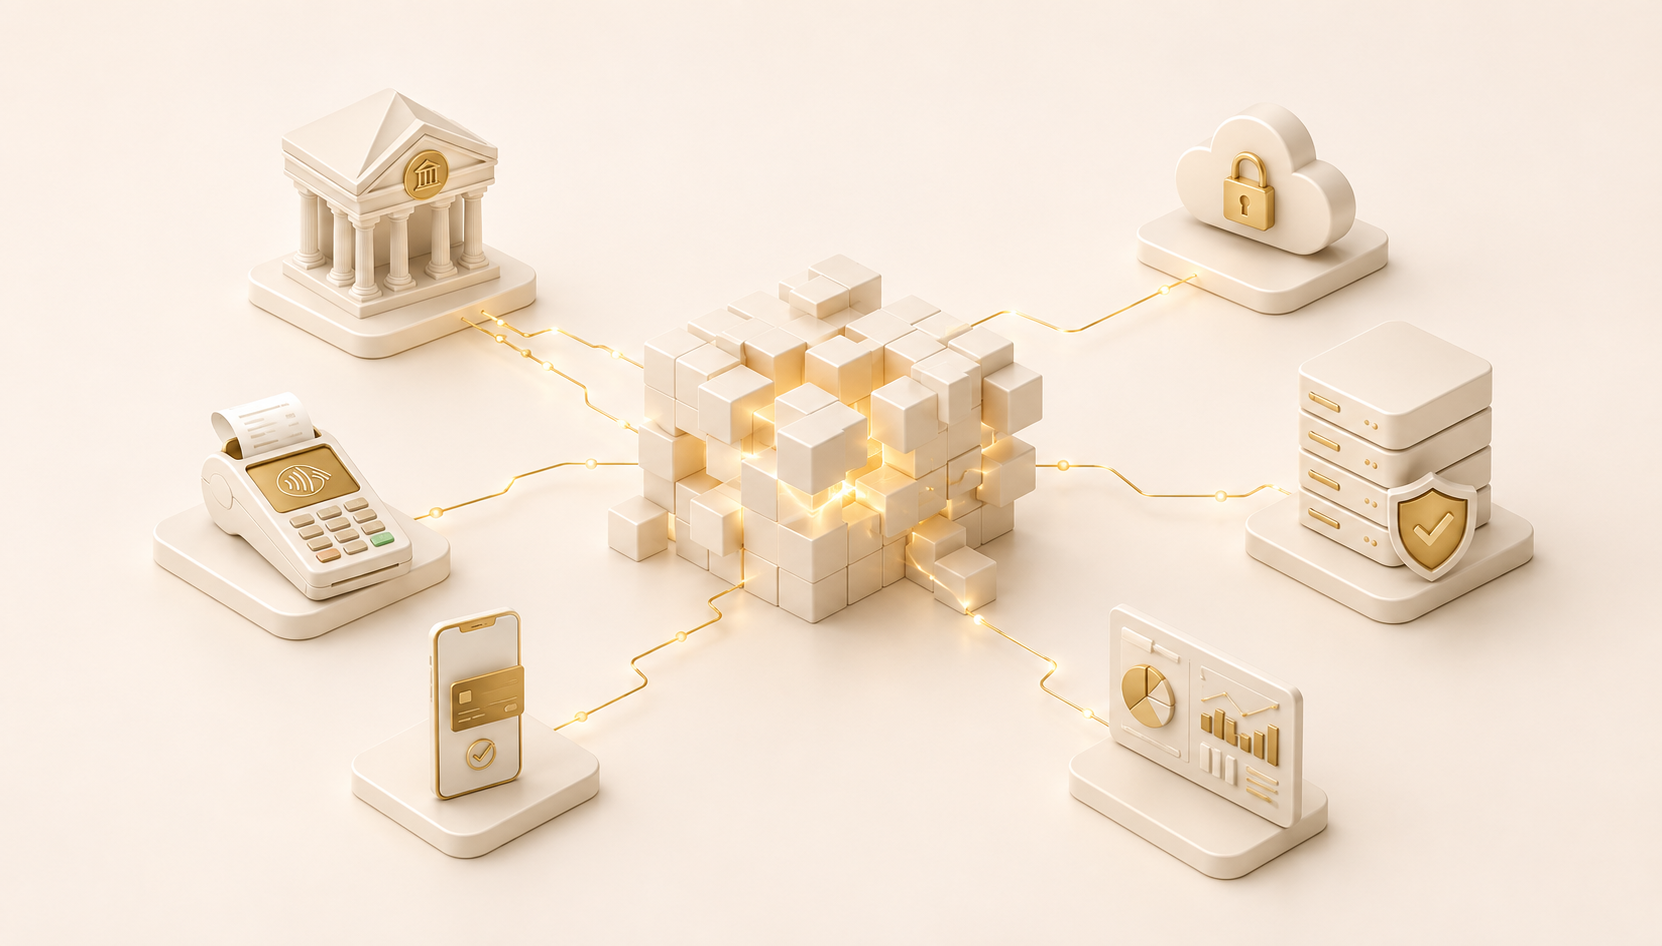
For banks, fintechs, and enterprises, this creates a new infrastructure challenge. Building payment capabilities is no longer only about supporting more payment methods. It is about connecting payments, data, compliance, identity, settlement, and financial workflows in ways that can operate across increasingly interconnected markets.
The future of payments, therefore, may not belong to a single new payment rail.
It may belong to the infrastructure that allows different rails, networks, institutions, and financial services to work together seamlessly.
And that is where the next generation of embedded banking solutions is likely to evolve: from isolated payment capabilities into connected financial infrastructure designed for a borderless, real-time economy.




Need Additional Help?
We're Here to Support You
Can't find what you're looking for? Our team is available to assist with engagement setup, advisory scoping, banking and payments infrastructure queries, compliance matters, and general technical support.